2024 Q2 Letter
Dear Partners, ████ and Friends,
The “snake” continues eating the “pig.” The market seems to be healthy. The “pig in the snake” market discussed in our Q3’23 letter, where the market (snake) is “digesting” the startups (pig) from the too-frothy days of 2021, continues—we’ve seen increasing levels of bridge rounds, down rounds, and shutdowns. This is to be expected and a healthy sign that markets are pricing appropriately.
However, not everything seems healthy. Only a few days after we sent out the Q1’24 letter, Pitchbook reported that, year to date, two venture funds, A16Z and General Catalyst, accounted for 44% of all LP capital to venture. “Assuming General Catalyst successfully closes its new vehicle on $6 billion, the two firms will have attracted a combined $13.2 billion,” Pitchbook said. This is huge but not totally unexpected. LP capital to venture is down, and there is a “flight to quality” dynamic where LPs retreat from riskier, emerging managers and move the diminished capital commitments to well-known, scaled funds that have decades of performance to lean on.

If this concentration persists and the top 10-20 venture firms represent an overwhelming share of capital raised, and, assuming these top funds do not commensurately increase the number of early-stage investments they make per year, the number of Seed to Series B individual “check writers” (i.e., partners at a firm that sponsor a deal) will go down. There will be fewer people who can gain conviction about a startup and sponsor a fund’s investment. This, I believe, should lead to a structural increase in risk of early stage investing.
Early-stage VCs need more check writers because they need an investor to believe in the dream of what an early-stage company can become even when the metrics are a little too early and there is still a lot of risk. Fewer investments made by a smaller set of investors should mean there are fewer people who can see the dream and write the follow-on check. This should mean a structural increase in risk associated with early-stage venture. Yet I do not see this risk being priced into rounds. While every other investing stage has seen price declines over the last two years, Seed and A have not (see exhibit). I don’t know what to make of this.
████████████ ████ ███████ ██ ███ ██████ ████████ ██ ██████████ ███ ██ ███ ███████ ██ ██ ██████ ██ ███ ████ ██ █████ ██ ████ █████ ███████ ██ ███ █████ ████████ ██ ████████ ███ ██████████ ██ ███ ███████ █████████ █████████████ ██ ███ ███████ █ █████ ███ ██ ███████████ ████ ███ ███████ ███████ ██ ████████ ██ ████ ███████ ███ █████████████

Our deepening understanding of the opportunity
In our Viewpoint pitch deck, we talk about how being thesis driven is our superpower and gives us an edge.
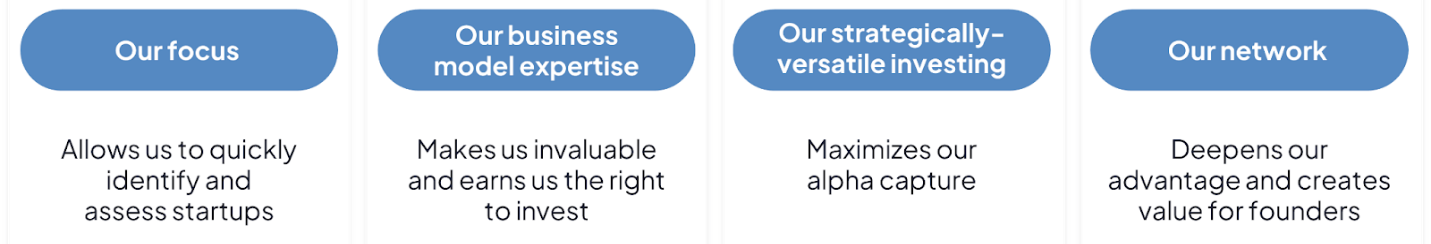
Over the last year, it’s become clear that Viewpoint’s edge has its own flywheel. The more startups we see that touch our thesis, the more deeply we understand the opportunity we are going after. This gives us an ever-sharper edge, which shows in the evolution of our thesis.
Thesis evolution: from distribution to producers
The original insight came in 2016 while I was at AXA Venture Partners (AVP). Ultimately, I took the learning and a deal that embodied it, Bold Penguin, to AmFam Ventures in early 2017. The insight: While customer acquisition (distribution) is difficult in most markets, it is particularly difficult in insurance and asset/wealth management (my focus at that time).
The difficulty of distribution (finding clients) meant that any business with a proprietary path to controlling large amounts of distribution would do best by focusing on that. These rare companies with access to distribution could use it as leverage, ultimately extracting a disproportionate amount of the margin from manufacturers. In special situations, this could unlock a powerful flywheel: Businesses with proprietary distribution capabilities would be sought by manufacturers and could charge ever-greater amounts for access to it, giving them increased economics, which they could use to gain ever-more distribution and charge ever-higher rates. Ultimately, these businesses could use this flywheel to become massive with powerful moats. I searched only for companies that had proprietary distribution, repeating ad nauseam the phrase that has become something of a mantra at Viewpoint: Distribution is the only thing that matters.
The prevailing wisdom then was that human agents—producers—were going to disappear. Yet, when I looked, it seemed that they were the key to the most successful distribution. I wanted to know why everyone thought they were going away. Why had they not gone away yet? Over 6 years and hundreds of conversations, I realized that human producers had “superpowers” that D2C brands could not access:
• Producers tap non-scaled idiosyncratic lead channels. They try lots of ways to acquire customers and eventually, for the good producers, they create a few sustainable lead sources.
• They benefit from superior unit economics. Human-to-human selling improves conversion rates, reduces client churn, and unlocks referrals as a powerful, low-cost growth driver.
• They close. Producers are only paid on success, so they go the extra mile to complete the transaction. This is particularly important in complex markets with multiple counterparties, especially when objections, cold feet, or bureaucratic challenges arise on every deal (e.g., real estate).
All this — my narrow focus on distribution (the only thing that matters) and my conviction in the staying power of human producers (who have superpowers) — made me realize I had a thesis around which I could build a fund. The fact that virtually no other VC fund was interested in human producers increased my conviction that, if I was right, our returns could dramatically outperform.
Now, 2.5 years, seven portfolio companies, twelve investments, and over a thousand startup evaluations later, we continue to gain new insight into how massive the opportunity in front of us really is.
In short, (1) the size and the impact of the successful companies within our thesis is even bigger and more important than we originally thought, (2) there are more producer-led industries than we originally thought, and (3) AI is poised to supercharge our thesis.
The winning companies will be even bigger and more important than we thought
The last 2.5 years of living within our thesis—via the investments we’ve made and the companies we’ve evaluated—has increased our conviction that our models aren’t just good businesses we could access at great prices because they had been overlooked by traditional venture funds. They are the best businesses in their respective industries. Startups in our thesis that achieve initial scale access a powerful flywheel propelled by ever-increasing scale, technical interconnectedness, and tech-driven efficiencies. This leads to the complete transformation of industries, similar in scale and impact that Uber had on the taxi industry.
How these startups gain initial scale is almost always unpredictable. In Bold Penguin’s case (within the small business insurance market), it was accessing a previously inaccessible pool of premium. For Turtlemint (personal insurance in India), a major regulatory change created an opportunity. For PLACE (residential real estate), who would have guessed that Ben Kinney and Chris Suarez were so good at what they did running their own brokerages that top-performing teams would give up 50% of their net income for just coaching (PLACE’s initial product)? George, founder of HealthSherpa, had to pivot eight times before he cracked the code for accessing individual health insurance agents. This unpredictability is the major reason why Viewpoint is not an early-stage focused fund; we wait until we see the flywheel — which we find earlier than others because we know where to look, we know how to recognize it, and our experience and thesis enables strong conviction, even when, as is usual, revenue greatly lags the flywheel.
Now that we’ve seen the flywheel play out many times over the last seven years, it's clear that we are tapping into a dynamic that is industry-agnostic. Industry-specific context and nuance are important and lead to different expressions of the flywheel, but it almost always appears as powerful as we thought. A tech-enabled platform that gains initial distribution will tap into a network effect. More distribution makes more supply want to connect to the platform. More supply on the platform and ever-better tech-enabled product will drive ever-more distribution to the platform. Eventually, the platform’s importance to the industry changes from “nice-to-have” to “must-have” for both distribution AND supply, and the startup has forever altered the industry.
There are more producer-led industries than we thought
It isn’t random that we, originally insurance investors, developed this thesis. Unlike other markets, insurance is massive, has lots of sub-markets, and producers are absolutely critical to each sub-market. We knew that insurance would keep us busy for years. We quickly recognized the “big 3” producer-led industries—insurance, real estate and wealth management—because their markets are massive, and most people recognize the value of the human producer. We now recognize the opportunity as even more enormous. For example, virtually every luxury purchase is intermediated by an agent (including art, private jets, watches, jewelry, collectibles, firearms and others) and talent agents, recruiters, and virtually every form of multi-level marketing distribution is powered by producers.
Believe it or not, travel agents (now called “advisors”) still exist and control $100B in annual spend across three submarkets: (1) luxury, (2) group, and (3) “fun in the sun” (all inclusive & cruises). Our research convinces us that these human advisors are likely to remain important in these segments.
Small business operators are probably the largest single category of producers we haven’t even started to touch. In these spaces, virtually all owners of home services companies (plumbers, electricians, appliance sales and installation, HVAC, etc.) as well as small businesses where the owner gets paid for success like interior designers, local tax and estate planners, small brand agencies, all look like “producer-led” industries. In virtually every case, the founder is paid on the net income the business generates, yet they aren’t scaled enough to create their own technical infrastructure. These are the environments in which Viewpoint looks to create industry-defining companies.
AI is poised to supercharge our producers
Over the last year, we’ve spent a lot of time assessing GenAI's impact on our thesis. AI is going to speed up, streamline, and dramatically improve a lot of producer tasks. The two critical things AI is structurally not able to help with are (1) the human-to-human, relationship-building parts of the lead channel and (2) prospect development, cultivation, and closing. This is because these steps rely heavily on emotional intelligence, trust-building, and nuanced understanding of human behavior, which are areas where AI still significantly lags behind human capabilities. Additionally, much of this relationship building happens in physical, real-world settings like on the golf course, over dinner at home, or at community events. The unique ability of producers to empathize, build rapport, and navigate complex social dynamics is irreplaceable by AI. This human touch is crucial in persuading clients, understanding their unspoken needs, and closing deals that involve high stakes or emotional investment.
What dawned on us only recently, as we’ve started to see incredibly exciting AI projects go into live production at our portfolio companies, is how big of an AI play we might have in front of us. As AI continues to evolve, it will not only enhance operational efficiencies but also open up new opportunities for producers to leverage AI tools to augment their capabilities. This means that producers can handle more clients, process information faster, and offer more personalized services, all while maintaining the human touch that makes them so effective. AI-driven analytics can provide producers with deeper insights into customer behavior and preferences, allowing for more targeted and effective marketing strategies.
AI should help the best producers become even more effective and efficient — driving the flywheel that powers the startups we fund ever-faster.
Full steam ahead
The Viewpoint team has been plenty busy over the last quarter. I’d like to thank all of you that were able to attend our inaugural LP Event in late June. We’re thrilled with the positive feedback we’ve received after the event; after living and breathing our thesis for a full day, it seems as though the event brought to life the opportunity that we’re so excited about.
We are just as excited about what we have coming up in the third quarter. In addition to a few high priority deals we’re currently working on, we’re getting ready for our annual Strategy, Corporate Development and Innovation Summit (that many of you attended last year) at InsureTech Connect in Las Vegas in October. Additionally, based on the strong reception we’ve received on our newly-launched Viewpoint AI Corner—where we present a new insurance-focused AI application each month—we expect to continue it through at least the end of 2024. If there are specific AI applications you’d like us to feature, please let us know!
████████ █████ █████████ ███ ███ ██████ ██ ███ ██████ █████ █████████ ████ ███ ██ ██████ ████ ██ ██ ██ ████ █████ █████ ████ ████ ██ ██ ███ █ ██████ ██ █████ █████ █████ ████ ████ ███████ ██ █████ █████ ████ ██ ████ ███ ██████ ███████
As always, thank you for your partnership and support.
Fondly,
Drew Aldrich, Managing Partner
Building in a producer
market? Let’s talk